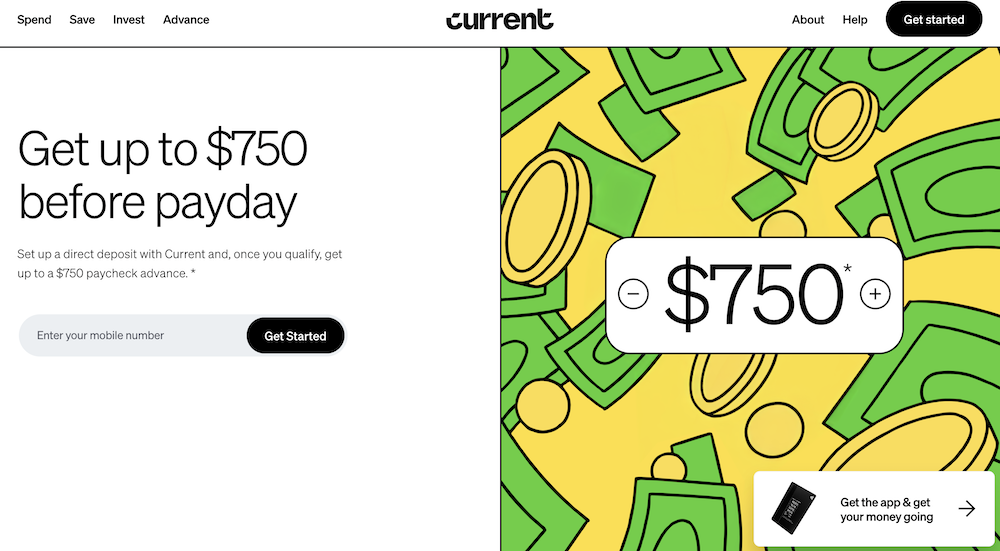
Current is a mobile banking app built around one promise: get your money faster. The checking account pays you up to two days early, and if you are short before payday, the built-in Paycheck Advance feature can send you up to $750 with no credit check and no interest.
That combination, a real checking account plus an on-demand advance, is why Current shows up so often next to apps like EarnIn and MoneyLion in the cash advance conversation. Current is not a payday loan and it is not a credit card. It is a bank account with a cash-flow tool built in.
This review breaks down exactly how Current's Paycheck Advance works, what the checking account offers, who qualifies, and where it falls short. Let's get into it.
- No interest on cash advances
- Advances of up to $750 (based on eligibility)
- 100% free, no catch
What Is Current and How Does It Work
Current is a fintech company, not a bank. Your checking account and debit card are issued by Choice Financial Group and Cross River Bank, both FDIC members, so your deposits are covered the same way they would be at a traditional bank.
Once you set up direct deposit, Current releases the money as soon as your employer sends it instead of waiting for the funds to officially settle. That is what gets you paid up to two days early. The same direct deposit history is also what unlocks Paycheck Advance and the account's other perks.
If you have looked at instant cash advance apps before, Current works differently than most. It is not a standalone advance app you bolt onto your existing bank. You move your direct deposit to Current, and the advance is a feature of that account rather than a separate subscription.
Eligibility for Paycheck Advance
Current keeps the eligibility bar low, but it is specific. According to Current's Paycheck Advance Terms and Conditions, you need to meet all of the following:
- Be 18 or older with a valid U.S. residential address and Social Security number
- Have access to the Current app
- Receive at least one Eligible Payroll Deposit of $200 or more into your Current account
- Have repaid any previous Paycheck Advance, plus any instant delivery fee, within 40 days
- Not live in Connecticut, Maryland, Nevada, Wisconsin, or Washington D.C.
Notice what is not on that list: no credit check, no minimum credit score, no proof of employer. Current decides your “Available Amount” using your deposit history and account activity, and that number can move up or down over time. Peer-to-peer transfers like Venmo, Zelle, or Cash App do not count as an Eligible Payroll Deposit, so a real payroll or government-payer direct deposit is required.
- No interest on cash advances
- Advances of up to $750 (based on eligibility)
- 100% free, no catch
Current Paycheck Advance: How It Works
How Much You Can Borrow
Current advertises Paycheck Advance up to $750. Your actual “Available Amount” is set by Current based on your deposit amount, deposit frequency, and account history, so a new user will likely see a lower number than the full $750 at first. You can check your current limit any time inside the app.
Delivery Speed and Fees
Standard delivery costs nothing and typically lands in your Current account within three business days. If you need the money sooner, Current offers an optional instant delivery that usually arrives within minutes, though it can take up to an hour. That speed comes with an “Instant Access Fee,” and the exact dollar amount is shown to you in the app before you confirm the request, so it can vary. You are never required to pay it. If three days works for your situation, the advance is completely free.
No Interest, No Credit Check, No Collections
Current calls Paycheck Advance an earned wage access service, not a loan, and its terms back that up. There is no interest charged, ever. Repayment is pulled automatically from your next Eligible Payroll Deposit, usually within 40 days (34 days if you live in California), or you can repay early yourself in the app.
Here is the part that matters most if you are worried about worst-case outcomes: Current's own terms state it has “no legal, equitable or contractual claim or remedy” against you if you do not repay. It will not send your unpaid advance to collections, will not sell the debt, and will not report it to a credit bureau. The consequence for not repaying is simple. You get locked out of new advances until the balance is cleared. That is a real difference from a payday loan, where nonpayment can mean fees stacking on fees and calls from a collector.
Want to see how that stacks up against other apps before you decide? Our best cash advance apps roundup compares the fee structures side by side.
The Current Checking Account

Paycheck Advance is only half the story. Current's checking account has its own set of features built to keep you out of overdraft trouble in the first place.
Overdrive: Fee-Free Overdraft
Current's overdraft feature, called Overdrive, lets your balance go negative without charging you an overdraft fee. To qualify, you need the same $200-or-more in eligible direct deposits over a rolling 35-day period, and you get 60 days to bring your balance back to zero. Current does not publish a fixed dollar cap for Overdrive online. Your specific limit is set by Current and shown in the app, so check there for your actual number rather than assuming a figure.
Savings Pods
Current lets you split savings into individual “pods” and pays up to 4.00% annual interest on balances up to $2,000 per pod, for a maximum of $6,000 earning the boosted rate across pods. That top rate also requires the same $200-plus qualifying direct deposit over 35 days. Without it, pods earn a lower base rate of 0.25%. Anything above the $2,000-per-pod threshold earns 0%, so this works best as a bucket for short-term goals rather than a place to park a large emergency fund.
Fee-Free ATMs and No Monthly Fee
Current gives you access to more than 40,000 fee-free ATMs nationwide through the Allpoint network, plus cash deposit options at retailers like CVS, Walgreens, and McDonald's. Current's own site advertises no monthly maintenance fee and no minimum balance requirement for the standard account. We could not find a separate published fee schedule confirming that in writing beyond the marketing page, so if a fee-free account matters to you, double check the current terms in the app before you switch your direct deposit over.
Where Paycheck Advance Is Not Available
Paycheck Advance is not offered to residents of Connecticut, Maryland, Nevada, Wisconsin, or Washington D.C. Current's checking account itself is still available in those states. It is only the advance feature that is restricted, based on state-level rules around earned wage access products. If you live in one of those states, our MoneyLion review and Brigit review cover two alternatives that operate under different terms.
Current Pros and Cons
Pros:
- Up to $750 Paycheck Advance with no interest
- No credit check, and it will not affect your credit score
- Standard delivery is free
- Non-recourse: no collections, no debt sale, no credit reporting if you cannot repay
- Paid up to 2 days early with direct deposit
- Fee-free overdraft through Overdrive
- 40,000+ fee-free ATMs
Cons:
- Requires moving your direct deposit to Current to unlock the best features
- Instant delivery fee is not published as a flat number, shown only in the app
- Overdrive's exact dollar limit is not disclosed publicly
- Not available in Connecticut, Maryland, Nevada, Wisconsin, or D.C.
- Savings Pods only pay the top rate on the first $2,000 per pod
None of those cons are dealbreakers on their own, but they add up to one theme: Current wants your full direct deposit relationship, not just a one-time advance. If you are not ready to move your paycheck over, a standalone app might fit better. Our best cash advance apps guide covers options that do not require switching banks.
Current Alternatives
Current is a strong pick if you want your advance built into a full checking account. If that is not what you are looking for, here are a few apps worth comparing:

- EarnIn: No subscription and free standard transfers, but it verifies your hours worked instead of your deposit history, so it is stricter about eligibility. Read our full EarnIn review for the details.
- MoneyLion: Another banking-plus-advance app, with a broader range of financial products including credit builder loans. See our MoneyLion review.
- Brigit: Works alongside your existing bank account instead of requiring you to switch, but charges a monthly subscription fee. Our Brigit review breaks down the plans.
- Cleo: A budgeting app with a cash advance feature attached, better suited to people who want spending insights along with the advance. Full details in our Cleo review.
- More small-dollar options: If $750 is more than you need, our roundup of $100 loan instant apps covers smaller advances, including where Current fits among them.
Each of these works a little differently. Compare the fees and eligibility rules before you commit your direct deposit to any one of them.
FAQs
Up to $750, though your actual Available Amount depends on your deposit history and is set by Current in its sole discretion. New users typically start lower than the $750 maximum.
No. Paycheck Advance is not a loan, so there is no interest. The only optional cost is the Instant Access Fee if you choose expedited delivery instead of the free three-day standard transfer.
Current will not send you to collections, sell your debt, or report it to a credit bureau. You simply will not be able to receive another Paycheck Advance until the outstanding balance is paid.
The checking account is widely available, but Paycheck Advance is not offered to residents of Connecticut, Maryland, Nevada, Wisconsin, or Washington D.C.
Yes. Current is a fintech company, not a bank, but your account and debit card are issued through Choice Financial Group and Cross River Bank, both FDIC members, which provide pass-through deposit insurance up to $250,000 under applicable conditions.
The Bottom Line on Current
Open Your Current AccountUse Current if
You get paid by direct deposit, you are comfortable moving that deposit to a new bank, and you want an advance option built into your everyday checking account instead of a separate app to manage. The fee-free overdraft and early paycheck access are worth it on their own, and Paycheck Advance is a bonus on top.
- No interest on cash advances
- Advances of up to $750 (based on eligibility)
- 100% free, no catch
Skip Current if
You live in Connecticut, Maryland, Nevada, Wisconsin, or D.C., where Paycheck Advance is not offered, or you do not want to switch your direct deposit away from your current bank just to get an advance. In that case, an app like Brigit that works alongside your existing account, or our full best cash advance apps comparison, is the better starting point.
