Most people who search for a MoneyLion review are not shopping for a checking account. They are short on cash, rent is due, and they want to know one thing: how much will MoneyLion actually front me, and what does it cost?
So that is where this review starts. The product you came for is called Instacash, and it advances cash against money you are already expecting, with no interest and no credit check. Here is the part most reviews leave out: a single advance is capped at $100 (it varies by state), and you take multiple advances until you hit your total limit. That total limit starts around $500, can reach $700 with a Credit Builder Loan, and can reach $1,000 with a MoneyLion Spend account and qualifying recurring direct deposits, according to MoneyLion’s own Instacash page.
The rest of the app is a stack of separate products with separate price tags, and a few of them cost real money every month. This review breaks out what each one costs, cites the page the figure came from, and tells you where the catches are.
MoneyLion Review at a Glance
Our rating: 4.5 out of 5. Instacash itself is the best part of MoneyLion: a real cash advance with no interest and no credit check, and the free account and free standard delivery now cost nothing extra. What holds the score down is the distance between the marketing and the mechanic. MoneyLion advertises advances up to $500, $700, or $1,000, but a single request tops out at $100, so reaching those totals means several separate requests, each carrying its own Turbo fee if you want it fast. Layer in a $19.99 a month credit-builder membership and a $9.99 a month rewards membership that only pay for themselves under specific conditions, plus a settled CFPB enforcement action and an active New York Attorney General lawsuit, and MoneyLion earns solid but read the fine print, rather than best in class.
Price: Instacash and the MoneyLion Spend checking account are both $0. Optional tiers range from $1 a month (Managed Investing on small balances) up to $19.99 a month (Credit Builder Plus), and MoneyLion One runs $9.99 a month unless you qualify for the $500 direct deposit waiver.
Who it suits: Best for someone paid by direct deposit who needs $100 to $500 to bridge a short gap and does not mind requesting it in $100 pieces rather than one lump sum. Less suited to someone who wants a single large advance instantly, or who is shopping for a personal loan funded directly by the lender they apply with.
Key Takeaways:
- Instacash caps each single advance at $100 (varies by state). Your total limit across multiple requests can reach $500, $700 with a Credit Builder Loan, or $1,000 with a MoneyLion Spend account and qualifying recurring direct deposits.
- No interest, no credit check, and no mandatory fee on the advance itself. Instant delivery is the part you pay for.
- Turbo delivery runs $0.49 to $8.99 depending on the amount and where you send it. Tips are optional.
- MoneyLion has been owned by Gen Digital since April 2025. The paid membership tier that older reviews describe is gone.
- Instantly access up to $500 with no interest
- Includes a RoarMoney checking account
- Build credit with low-risk credit builder loans
- Earn cashback on everyday purchases
Who MoneyLion Is For (and Who Should Skip It)
The Gig Worker or Hourly Employee With Irregular Pay
If your paycheck timing is unpredictable and you occasionally need $50 to $100 to bridge a day or two before payday, Instacash is a strong fit. No interest, no credit check, and the free delivery window is often fast enough if you request early. It is worth comparing against a gig-focused option like our EarnIn review before you settle on one app. Verdict: use it.
Someone Who Needs $500 in One Shot for an Emergency
If you are picturing MoneyLion as a single $500 same-day advance, recalibrate. A single request caps at $100, so covering a $500 emergency in one sitting is not how Instacash works, and stacking five requests together costs more in Turbo fees than the marketing implies. If getting a larger amount fast matters more to you than avoiding interest entirely, compare it against our roundup of cash advance apps like Dave before you decide. Verdict: skip it for this specific need.
Someone Who Wants Free Banking With High App Store Ratings
If you mainly want a $0 checking account with no minimum balance, strong app store ratings, and Instacash as a backup rather than a primary plan, MoneyLion Spend is a reasonable fit. It costs nothing to open and nothing to maintain. If you are still comparing, our list of apps like MoneyLion is a good next stop. Verdict: use it.
Someone Shopping for a Personal Loan
If you came here expecting MoneyLion to lend you $1,000 to $35,000 directly the way older reviews describe, know that MoneyLion now runs a loan marketplace rather than lending directly, and it only shows you the lenders it has a deal with. Shop rates in more than one place, including through a roundup like our Brigit alternatives page, before accepting an offer. Verdict: treat MoneyLion as one quote among several, not your only stop.
What Is MoneyLion?
MoneyLion is a personal finance app that bundles a cash advance, a checking account, credit monitoring, a credit-builder loan, investing, and a loan marketplace into one login. It launched in 2013 as a lender and has since turned into a distribution platform that sells you other companies’ products alongside its own.
One thing worth knowing before you hand over your bank login: MoneyLion is no longer an independent company. Gen Digital, the company behind Norton and LifeLock, completed its acquisition of MoneyLion on April 17, 2025, paying $82.00 per share in cash for a transaction value of roughly $1 billion, plus a contingent value right worth $23.00 per share in Gen stock. That is straight from Gen’s investor relations announcement.
Practically speaking, that means your MoneyLion data now sits inside an identity and security conglomerate, and the app has been steadily folded into Gen’s financial wellness pitch. It also means the product names have shifted. If you used MoneyLion years ago, the account you remember as RoarMoney is now branded MoneyLion Spend, and the paid membership tier this site once covered is no longer offered at all. It does not appear anywhere on MoneyLion’s current product lineup or pricing page.
How Instacash Works
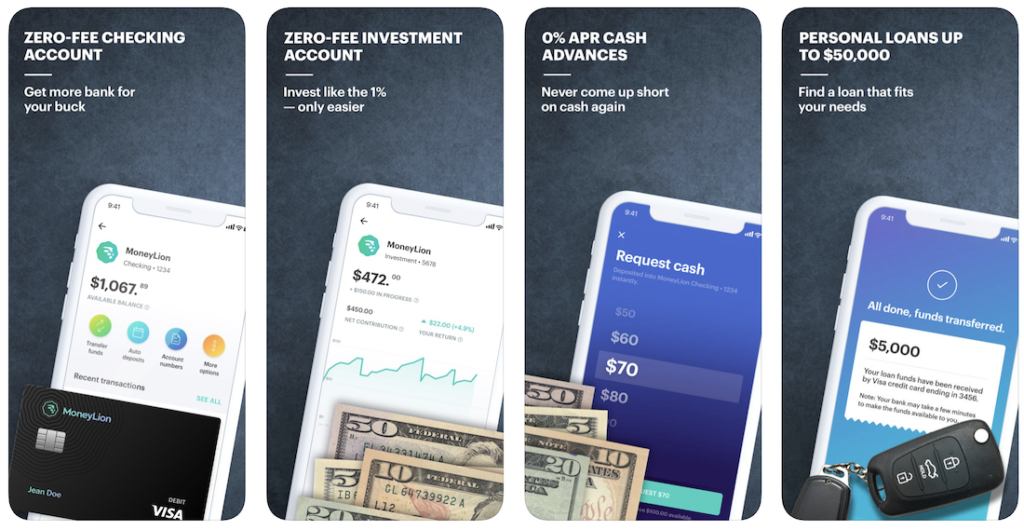
Instacash is the reason most people download this app. It is a cash advance against money you are already expecting, and MoneyLion describes the terms plainly on the Instacash page as “No interest. No credit check. No mandatory fees.”
Unlike a payday loan app that charges a finance charge, there is no APR on the advance. MoneyLion pulls the repayment on your next expected payday. If the money is not there, the collection attempt fails and you are locked out of further advances until the balance clears, which is the practical risk with every product in this category.
Instacash Limits: $100 Per Advance, Up to $500 to $1,000 Total
Here is the mechanic most reviews of this app skip entirely. MoneyLion’s own Instacash page says it plainly: “You can request up to $100 per advance (varies by state) and take multiple advances until you hit your total limit.” A single request tops out at $100. Your total limit, the ceiling across all your advances combined, is a separate number that climbs in three steps: a base account with qualifying recurring direct deposit into an external checking account can reach up to $500, taking a Credit Builder Loan raises that ceiling to as much as $700, and adding a MoneyLion Spend account with its own qualifying recurring direct deposit raises it again, to as much as $1,000.
Nobody starts at the top of any of these tiers. MoneyLion assigns your actual limit based on income and account history, so a new user may be approved for far less than the maximum even after qualifying for a higher tier. And because every advance still tops out at $100 per request, getting to $500 means at least five separate requests, not one, each with its own Turbo fee if you want it delivered instantly.
How to Get an Instacash Advance
- Download the MoneyLion app and open a free account. There is no membership purchase required to reach Instacash.
- Connect the checking account your paycheck hits, or open a MoneyLion Spend account inside the app.
- Let MoneyLion review your deposit history and assign your limit. This is a cash-flow review, not a credit pull, so it does not touch your credit score.
- Request the advance and pick a delivery speed. Free is slower, Turbo is instant and costs a fee. Each request is capped at $100, so reaching a higher total limit takes multiple separate requests.
- Add a MoneyLion Spend account and a qualifying recurring direct deposit, or take a Credit Builder Loan, if you want to work toward the $700 to $1,000 ceiling.
Instacash Fees: Turbo Delivery and Tips
“No mandatory fees” is accurate, and it is also where the money is made. MoneyLion charges nothing to move an advance on its normal schedule, and charges you to skip the wait.
Per the Instacash page, regular delivery costs $0 either way. To a MoneyLion Spend account it lands in about two business days. To an external checking account it takes about five business days. That second window is the one to watch, because a five business day wait on a Friday request is useless if you needed the cash for the weekend.
Turbo delivery arrives within minutes, and the fee is tiered by how much you request and where it is going, according to MoneyLion’s pricing page. Fees vary by state.
| Advance Amount | Turbo Fee to MoneyLion Spend | Turbo Fee to an External Account |
|---|---|---|
| $5 or less | $0.49 | $1.99 |
| $10 to $25 | $1.99 | $3.99 |
| $30 to $45 | $2.99 | $4.99 |
| $50 to $65 | $3.99 | $5.99 |
| $70 to $85 | $5.49 | $7.49 |
| $90 to $100 | $6.99 | $8.99 |
Run the math before you tap Turbo. A $6.99 to $8.99 fee to move $90 to $100 instantly is a very expensive week of waiting. The fee does not change based on how long you keep the money, which means the effective cost of borrowing gets worse the smaller and shorter the advance is. And because every advance is capped at $100, hitting a $500 total limit with Turbo delivery every time means paying one of these fees up to five separate times.
There is also a tip. MoneyLion states that “every time you take an interest-free cash advance, you will have a choice to leave a small optional tip.” It is genuinely optional, and MoneyLion commits in writing that “Whether you choose to tip and/or pay a Turbo fee for expedited delivery does NOT impact your access to Instacash or your Instacash limit.” Set it to zero if you want. Nothing about your limit changes.
- Instantly access up to $500 with no interest
- Includes a RoarMoney checking account
- Build credit with low-risk credit builder loans
- Earn cashback on everyday purchases
MoneyLion Spend: The Account That Raises Your Limit
MoneyLion Spend is the checking account formerly sold as RoarMoney. It is the account that unlocks the higher Instacash ceiling and the faster free delivery window, so it matters even if you have no interest in switching banks.
The monthly administrative fee is $0 on MoneyLion’s pricing page. That is a real change from the RoarMoney era, when the account carried a small monthly charge, and it removes the main reason to avoid opening it purely as an Instacash on-ramp.
Sitting above the free account is a paid tier called MoneyLion One, that costs $9.99 a month, or nothing at all if at least $500 of direct deposits land in your MoneyLion Spend account in a given month. If your paycheck is direct deposited and clears $500 a month, the premium tier costs you nothing. If it does not, you are paying $119.88 a year. The centerpiece perk is 1% cash back on qualifying purchases, capped at $30 in cash back per month. To earn back the $9.99 fee in cash back alone you would need roughly $999 in qualifying spending that month, and the $30 cap means you can never get back more than that regardless of how much you spend beyond roughly $3,000. Unless the direct deposit waiver applies to you, or you specifically value the other perks bundled into the tier, the cash back alone will not cover the fee for most users.
MoneyLion Memberships and What They Cost
This is the part of the app that trips people up. Instacash is free to access, but MoneyLion sells several recurring subscriptions alongside it, and they are easy to enroll in while you are moving fast through the app. Every figure below is from MoneyLion’s own pricing and product pages.
Credit Builder Plus: $19.99 a Month
Credit Builder Plus is a membership that comes with a credit-builder loan reported to the bureaus. The membership costs $19.99 per month and the loan carries an APR of 5.99% to 29.99%, per the pricing page.
One more wrinkle worth knowing: a fully secured Credit Builder Loan can disburse $0 to you upfront, with the full loan amount held in a Credit Reserve Account until your payments are complete. In that structure you are paying $19.99 a month plus interest to build payment history, not to receive cash in hand. Confirm which structure applies to your loan before you sign up expecting money up front.
Price that honestly. The $19.99 is the real cost, not the APR, and it is charged whether or not your score moves. That is $239.88 a year to have one installment account reported. Several standalone credit-builder products cost a fraction of that, so this only makes sense if you are also using the rest of the membership. Do not sign up for it as a cheap credit fix, because it is not one.
WOW Membership: $9.99 a Month
WOW is MoneyLion’s rewards membership and the closest thing to a successor to the old premium membership. MoneyLion’s WOW page prices it at “$9.99/month billed monthly,” “$54.90 for a six-month term,” or “$99.99 for an annual term.”
As of this update, WOW is still priced on MoneyLion’s site, though it does not appear in the site’s current navigation and some of MoneyLion’s own material describes it in past tense. That is not the same as confirmed discontinuation, so treat WOW’s current status as unclear rather than assuming it is either fully active or gone, and verify directly with MoneyLion before enrolling.
The perks include cashback on qualifying purchases, 1% Bitcoin back on crypto buys, a waived Managed Investing fee, refunded foreign transaction fees on MoneyLion Spend purchases, and a rebate of up to $5 on your first Turbo fee and every tenth one after that. That last one is the only perk directly relevant to the cash advance, and a $5 rebate every tenth advance does not come close to covering a $9.99 monthly fee. Skip it unless you want the investing and cashback side.
Managed Investing: $1 to $5 a Month
MoneyLion’s managed investment account is priced by balance: $1 a month on accounts up to $5,000, $3 a month on accounts over $5,000 up to $25,000, and $5 a month above $25,000.
On a small balance that flat fee is brutal in percentage terms. $1 a month on a $200 account is 6% a year in fees. The tiers only get reasonable once you have real money in the account, and by that point you have cheaper options elsewhere.
Personal Loans Through MoneyLion
Older reviews of this app, including the previous version of this one, described MoneyLion as making personal loans of $1,000 to $35,000 directly. That is no longer how it works and it is the single biggest thing outdated MoneyLion reviews get wrong.
MoneyLion now runs a loan marketplace. Its personal loans page advertises offers up to $100,000 and discloses that “ML Enterprise Inc. d/b/a Engine by MoneyLion… is not a lender and we do not offer financial products directly.” You are being matched to third-party lenders, and MoneyLion is paid for the referral.
So shop around. MoneyLion only shows you lenders it already has deals with, not every lender out there, and the rate you see here may not be the best one you can get. Check at least one other place before you sign anything. Our personal loan guide walks through how to compare offers without tanking your credit score.
MoneyLion App Ratings
App store scores are worth checking on any cash advance app, because the review sections are where repayment and lockout complaints surface first.
On the App Store, the app is listed as “MoneyLion: Cash Advance App” by MoneyLion Inc and holds a 4.8 average from 328,085 ratings, according to Apple’s own app lookup data. On Google Play, the listing is titled “MoneyLion: Banking & Cash Back” and shows a 4.5 average from 219,315 ratings.
Both scores are high for this category. Treat them as a signal about the app experience rather than about pricing, since cash advance apps tend to prompt for a rating right after the money lands and before the repayment pull happens.
What’s Not Great About MoneyLion
The $100 Ceiling on Every Advance
MoneyLion’s own Instacash page is specific about the mechanic: “You can request up to $100 per advance (varies by state) and take multiple advances until you hit your total limit.” The $500, $700, or $1,000 headline is a ceiling on your account, not a lump sum you can pull in one request. Getting to $500 takes at least five separate advance requests, and if you want each one delivered instantly, that is a Turbo fee five times over. If your actual goal is a single $100 advance and nothing else, a dedicated option such as one from our roundup of $100 loan instant apps may get you there with less account setup.
Membership Costs Versus What They Deliver
MoneyLion sells three optional subscriptions on top of a free Instacash account: MoneyLion One ($0 to $9.99 a month), Credit Builder Plus ($19.99 a month), and WOW ($9.99 a month, still priced on MoneyLion’s site though absent from its current navigation). Of the three, only Credit Builder Plus does something a free account cannot, and even that is a loan you are paying $19.99 a month to hold, on top of a 5.99% to 29.99% APR. WOW’s most advance-relevant perk is a $5 rebate on every tenth Turbo fee, which does not come close to paying for itself unless you are already using the cashback and investing side of the membership. Price out what you would actually use before enrolling in anything beyond the free account.
Regulatory History
MoneyLion settled a CFPB enforcement action over its old membership program, with a stipulated final judgment entered November 24, 2025, and $1.75 million in consumer redress. That is a settlement, not a finding of guilt. Separately, the New York Attorney General’s case against MoneyLion is still open: a federal court remanded it back to New York Supreme Court on November 12, 2025, after MoneyLion tried to move it to federal court. And two 2026 federal court rulings let cash-advance-related claims proceed past a motion to dismiss and past a motion to force arbitration, without ruling on the underlying merits. None of this changes how the base Instacash advance itself works, but it is worth knowing before you sign up for anything beyond it. More detail, with sources, is below.
Cash Advance Apps Like MoneyLion
If MoneyLion is not the right fit, these apps will spot you cash before payday without a credit check. Our full roundup of the best cash advance apps covers more of them side by side.

MoneyLion Review: Is it a Scam or Legit?
MoneyLion is legit and not a scam. It is a real, regulated financial platform, it has been operating since 2013, and it is now a subsidiary of Gen Digital, a publicly traded company. Instacash does what it says it does.
Legit is not the same as clean, though, and you deserve the full picture. The Consumer Financial Protection Bureau brought an enforcement action against MoneyLion and its subsidiary ML Plus, LLC over the old membership program, and that specific case is now resolved. The CFPB alleged violations of the Military Lending Act for “charging covered borrowers annual percentage rates that exceeded the allowable rate under the MLA and failing to make required disclosures,” and further alleged that the company trapped consumers in membership programs when they had unpaid balances and kept collecting membership fees after cancellation requests. A stipulated final judgment was entered on November 24, 2025, including $1.75 million in consumer redress. A stipulated judgment is a settlement; it is not a court finding that MoneyLion broke the law or an admission of liability by the company. The CFPB’s enforcement record lays out the case and the resolution.
A separate case is still active. The New York Attorney General sued MoneyLion, MoneyLion removed the case to federal court, and the federal court remanded it back to New York Supreme Court on November 12, 2025, under index 451303/2025. The federal docket shows the case as “terminated,” but that reflects the remand back to state court, not a dismissal and not a win for MoneyLion. As of this update, the case continues in New York state court.
Two other federal rulings are relevant here, both from the Southern District of New York: Burkhardt and Lowe. In each, a court allowed cash-advance-related claims to proceed and declined to force the dispute into arbitration, on the reasoning that advances like these function as credit. Both rulings are at the motion stage, meaning the court let the claims move forward rather than ruling on whether MoneyLion actually broke the law. Treat them as open litigation, not a verdict.
Note what the resolved CFPB case was about. It was the old membership subscription, not the cash advance, and the membership tier at the center of it no longer exists. The other matters above are separate and, apart from the CFPB settlement, unresolved. That history is still the right lens for using this app today: the advance is the honest part, and the recurring subscriptions and legal history are the parts to read twice.
Who MoneyLion Is Actually Good For
Use it if you want a no-interest advance and you are comfortable requesting it in $100 increments rather than one lump sum, you can wait the free delivery window, and you are disciplined about declining the upsells. Work toward the $700 or $1,000 ceiling with a Credit Builder Loan or a MoneyLion Spend account plus direct deposit if you need the headroom, since none of that costs anything extra to set up.
Skip it if you are looking at Credit Builder Plus as a cheap way to fix your credit, or if you expect to pay for Turbo on every small advance. In both of those cases the fees swamp the benefit. And if you are using advances every single pay period, the product is not the problem. Work on debt repayment and automated savings instead, because a free advance you take twelve months a year is just a smoother version of the same shortfall.
The app is free to download for iOS or Android, and you can reach Instacash without buying a membership.
- Instantly access up to $500 with no interest
- Includes a RoarMoney checking account
- Build credit with low-risk credit builder loans
- Earn cashback on everyday purchases

