Perpay is a shop now, pay later app that works differently from every other one you have heard of. You do not use it at another store's checkout. You shop Perpay's own marketplace, and the payments come out of your paycheck before the money ever reaches your bank.
That structure is the whole reason it exists, and it is why Perpay can say yes to people that Affirm and Klarna turn down. It is also the source of every complaint about it.
This review covers how it works, what it actually costs, who qualifies, and where it falls short, using Perpay's own help center and current reviews rather than a 2024 snapshot.
Perpay in four numbers
Verified September 2026
Spending limit
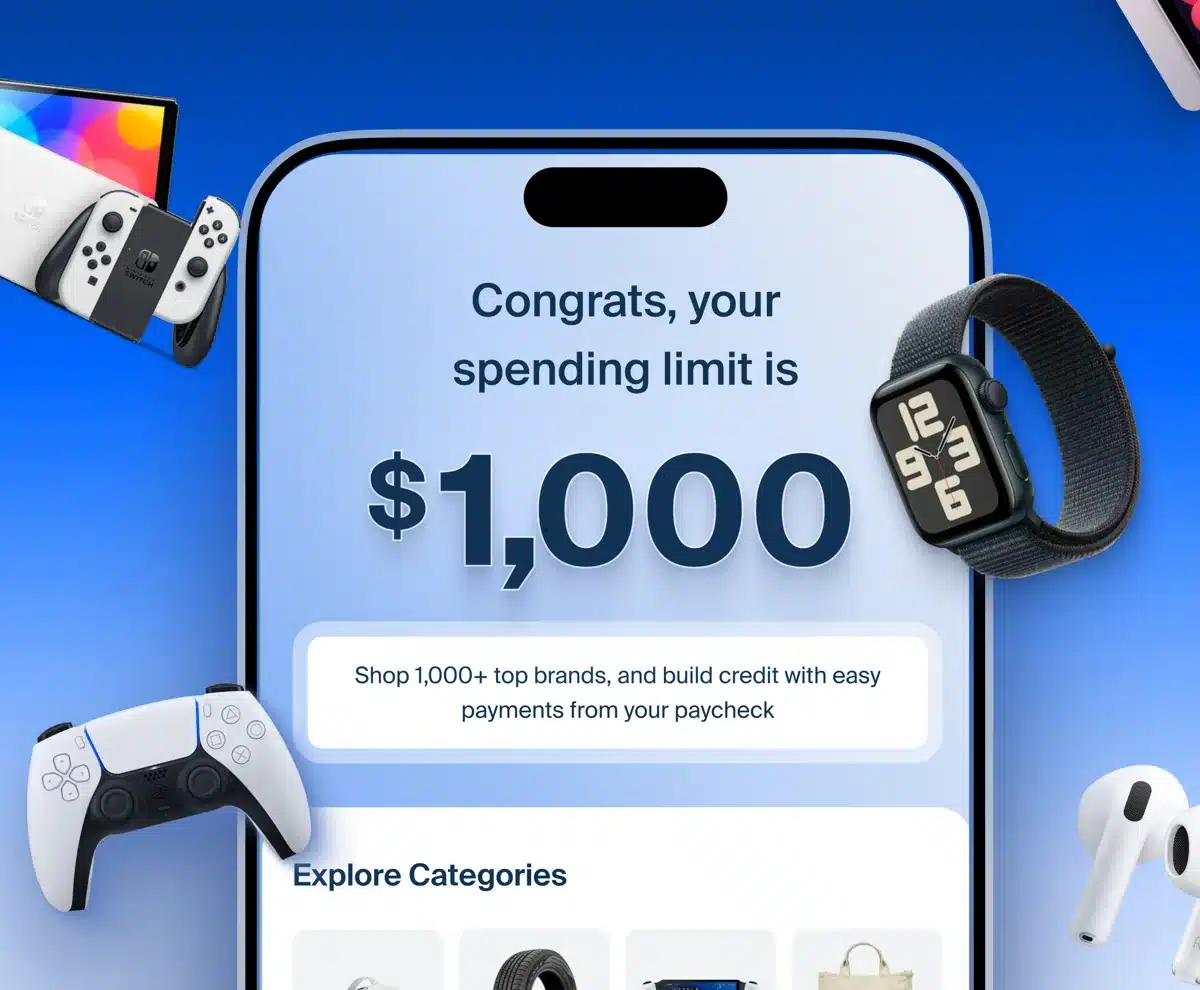
Up to $1,000
Estimated at signup, no hard pull
Marketplace cost
$0
No interest, no fees, no late fees
Credit reporting
$5 a month
Perpay+, all three bureaus
Trustpilot
4.7 of 5
4,096 reviews, 79% five star
The one requirement that decides everything: you need a W-2 job paid by direct deposit. If you are a contractor, gig worker, or self employed, Perpay is not for you, and the alternatives at the bottom of this page are.

- Spend up to $1,000 now and pay it off in small pieces taken from each paycheck automatically
- No interest, no late fees, and no fees of any kind on marketplace purchases
- Applying does not affect your FICO or Vantage score, so bad or thin credit is not a dealbreaker
- Perpay+ ($5 a month) reports your payments to Experian, Equifax and TransUnion, and members saw scores rise 30+ points on average in the first year
- The rest of your paycheck lands in your bank as usual, so it never touches the money you already budgeted
What Is Perpay?
Perpay is a closed marketplace. You buy from Perpay's own store, which carries more than 1,000 brands by its count, including Apple, KitchenAid and PlayStation, and you pay it off in pieces that are deducted from each paycheck automatically.
There is no interest and no fee on those purchases. Perpay makes its money on the products themselves, which is the honest way to understand the price complaints later in this review.
Two paid add-ons sit beside the marketplace: Perpay+ for credit reporting, and a separate Perpay credit card that has real fees and a real APR.
How Perpay Works
Perpay's help center lays out the process in five steps. Here they are without the marketing.
Create an account and get an estimated spending limit
No hard credit check
MinutesPerpay states plainly that it does not run a hard credit check with Experian, TransUnion or Equifax to set your limit. It may pull data from Clarity, a subprime data bureau, which is why its fine print says applying “will not affect your FICO or Vantage score” but “may affect your credit profile.”
Most new members see a limit up to $1,000. Perpay says placing orders and paying on time raises it over time.
Shop the marketplace and submit an order for review
An approvals team looks at every order
Same day to a few daysYou check out like any store, but the order goes to Perpay's Approvals Team rather than straight to shipping. Setup and employer verification are the most common complaint on Trustpilot, so expect this step to take longer if your payroll provider is obscure.
Point part of your paycheck at Perpay
A payroll direct deposit split
Set up onceOnce the order is approved you set up a small direct deposit from your payroll to your Perpay account. The rest of your pay lands in your normal bank as usual. If your employer will not split a paycheck, Perpay has a workaround covered in the FAQ below.
Your order ships after the first payday
Nothing ships on day one
About a weekThis is the part first time users miss. Perpay processes the order for shipment only after your first qualifying payment arrives on your next payday, and says orders generally ship within one week of that first deposit. If you need something today, this is the wrong tool.
Pay it off, then cancel the deduction yourself
The deduction does not stop on its own
Your jobPayments come out every payday according to the allotment you set. When the order is paid in full, Perpay's own instructions are to contact your employer or payroll provider to cancel the deposit. Put a reminder on the payoff date, because the money keeps flowing to Perpay until you do.
What Perpay Costs
There are three products under the Perpay name, and reviews that blur them together are why people get surprised. Here is each one on its own.
The marketplace
$0 interest, $0 feesBuying from the marketplace costs nothing beyond the price of the item. No interest, no fees, and no late fees, because payments are pulled from payroll before you could miss one.
The cost is in the prices. The most consistent criticism across Trustpilot, ConsumerAffairs and Finder is that marketplace prices run above what the same item costs at a normal retailer. Perpay does not publish a markup figure. Compare the exact model before you order, then decide whether the difference is worth interest free terms you could not get elsewhere.
Perpay+
$5 a monthPerpay+ is the credit building layer, and it is optional. For $5 a month, taken as about $2.31 per biweekly paycheck, Perpay reports your marketplace spending limit of up to $1,000 to Experian, Equifax and TransUnion within about 30 days of enrolling.
Perpay says members who enrolled saw their scores rise 30 or more points on average in the first year, a figure it bases on roughly 50,000 Perpay+ customers. Without Perpay+, nothing is reported and your on time payments build nothing.
The Perpay Credit Card
Different productThe Perpay Mastercard is a real credit card with real costs, and it is where the “no fees” reputation stops applying. Perpay's current terms: a variable APR of 27.74% to 29.99%, a $9 monthly account service fee starting your first month, a $9 opening fee deducted from your first direct deposit, and a $24 late fee. Returned payments are $24, foreign transactions are 3%, and a metal card is an optional $35. Limits start at $300.
Do the math before you take the card. $9 a month is $108 a year on a card that can start at a $300 limit, plus $9 to open it. It is a fee for access, not a reward card. If you only want the marketplace and credit reporting, Perpay+ at $5 a month does that without any of this.
Who Qualifies for Perpay
Perpay published its full eligibility list in March 2026. Every item below is from that list.
- 18 or older and a U.S. resident with a valid mailing address
- A mobile number with a U.S. carrier, not a VoIP line
- Full time W-2 employment in the U.S.
- Paid by direct deposit through a third party payroll system
- Able to split your paycheck into a second direct deposit, or use Perpay's Split program
- No active bankruptcy and in good standing on your obligations
Contractors, gig workers and the self employed are not eligible, with one narrow exception for business owners who pay themselves through a third party payroll provider. SSI, SSDI and VA benefits are accepted as qualifying income.
Two numbers you will see repeated on other sites, a three month minimum with your employer and a $15,000 minimum income, are not on Perpay's current eligibility page. They may apply in practice through the approvals process, but Perpay does not state them, so I have not either.
Is Perpay Legit?
Yes. Perpay is a real company that has been operating since 2017, it holds a 4.7 out of 5 on Trustpilot across 4,096 reviews as of September 2026, with 79% of reviewers giving five stars and 11% giving one, and its app shows a 4.9 rating from about 6,500 reviews.
It tells you upfront that it does not run a hard credit check, and its help center documents every fee quoted in this review.
The one star reviews cluster around two things, and neither is fraud. The first is account setup and employer verification, which can stall when Perpay cannot confirm your payroll.
The second is direct deposit timing, because nothing ships until your first payday payment clears, and people expecting a package in two days get frustrated.
The praise clusters too. Reviewers like that the money comes out before they can spend it, which makes budgeting for a big purchase automatic, and they like the range of the marketplace for a service that says yes to bad credit.
The Catch
Perpay is legit and it is also expensive in a way that does not show up as a fee. Read these three before you order.
The prices
Compare firstBecause the marketplace charges no interest, the margin is in the price tag. Reviewers across every major review site say the same item often costs more on Perpay than at a big box retailer. The difference is your real cost of borrowing. Price the exact model elsewhere and treat the gap as the interest you are paying.
Credit building is not automatic
$5 a monthPaying on time through the marketplace alone reports nothing. You have to enroll in Perpay+ and keep paying $5 a month for the tradeline to reach the bureaus. Budget for it as part of the purchase if credit is the goal.
You stop the deductions, not Perpay
Set a reminderWhen the order is paid off, Perpay tells you to contact your employer or payroll provider to cancel the allotment. Forget, and the next paycheck still sends money to a Perpay account you no longer owe anything on.
Perpay Pros and Cons
- No hard credit check, and applying does not touch your FICO score
- No interest, no fees and no late fees on marketplace orders
- Optional reporting to all three bureaus for $5 a month
- Payments are automatic, so you cannot miss one
- Works for SSI, SSDI and VA income
- Referral credits of $80 for inviting friends
- Marketplace prices commonly run above retail
- W-2 payroll direct deposit only, so no gig or contract income
- Nothing ships until your first payday payment clears
- Credit reporting costs extra and only happens with Perpay+
- The Perpay credit card carries $9 a month plus a 27.74% to 29.99% APR
- You must cancel the payroll deduction yourself when paid off
Perpay Alternatives
The right alternative depends on which half of Perpay you actually want.
Want the credit building without the payroll rule
KikoffKikoff builds credit from $5 a month with no employer involved, no paycheck split and a 45 day money back guarantee. It reports to the bureaus without you buying anything. Our Kikoff review covers the tiers.
See Kikoff plansWant a bigger, more traditional credit builder
SelfSelf runs a credit builder loan you pay into monthly and get back at the end, with a secured Visa available once you have built up savings. It is slower than Perpay but it does not depend on your employer. Details in our Self review.
Want buy now, pay later at normal stores
SezzleIf what you really wanted was to split a purchase at a retailer you already shop at, Sezzle and the other apps in our best buy now, pay later apps guide do that at retail prices. You will need decent enough credit to be approved, which is the tradeoff Perpay removes.
For the wider set of options, see our best credit building apps and, if the goal is the score itself, how to improve your credit score.
Perpay FAQs
Does Perpay check your credit?
Not with a hard inquiry. Perpay says it does not run a hard check with Experian, TransUnion or Equifax to set your limit and that applying will not affect your FICO or Vantage score. It may use data from Clarity, an alternative credit bureau.
What if my employer will not split my paycheck?
Perpay has a program for this called Split. Your full paycheck is deposited into a Perpay account held with JPMorgan Chase, Perpay takes its payment, and the rest is sent to your own bank the same day.
The marketplace works normally on Split. The Perpay credit card does not, unless your income is SSI, SSDI or VA benefits, because the card requires a deposit straight from payroll.
How long does Perpay take to ship?
Orders are processed for shipment after your first qualifying payment arrives on your next payday, and Perpay says they generally ship within one week of that first deposit. Plan on one to three weeks from ordering to delivery depending on your pay cycle.
Does Perpay have a referral program?
Yes. The current program, updated by Perpay in November 2025, gives you an $80 credit once a friend you invite makes their first qualifying direct deposit payment, and gives your friend a credit toward their first order.
Credits stack, but Perpay warns that using only part of a credit can forfeit the rest, so apply the full amount to one order.
Can I use Perpay with bad credit?
That is the customer it is built for. Approval rests on your job and payroll direct deposit, not your score. What bad credit does not change is the price of the items, so the compare first advice matters most for exactly the people Perpay approves.
Verdict: Is Perpay Worth It?
Perpay is worth it for one specific person: someone with a steady W-2 paycheck and weak credit who needs a particular item, cannot get approved by the mainstream BNPL apps, and is willing to pay marketplace prices to get interest free terms and, with Perpay+, a reported tradeline.
It is not worth it if you can qualify for Sezzle or Affirm at a normal store, if you are paid as a contractor, or if you would be taking the Perpay credit card for its own sake. And it is never worth it without checking the price of the exact item somewhere else first.
If you fit the first description, it does what it says, and the cost is visible up front rather than buried in interest.
- Spend up to $1,000 now and pay it off in small pieces taken from each paycheck automatically
- No interest, no late fees, and no fees of any kind on marketplace purchases
- Applying does not affect your FICO or Vantage score, so bad or thin credit is not a dealbreaker
- Perpay+ ($5 a month) reports your payments to Experian, Equifax and TransUnion, and members saw scores rise 30+ points on average in the first year
- The rest of your paycheck lands in your bank as usual, so it never touches the money you already budgeted